 by Amir Iqbal
Introduction
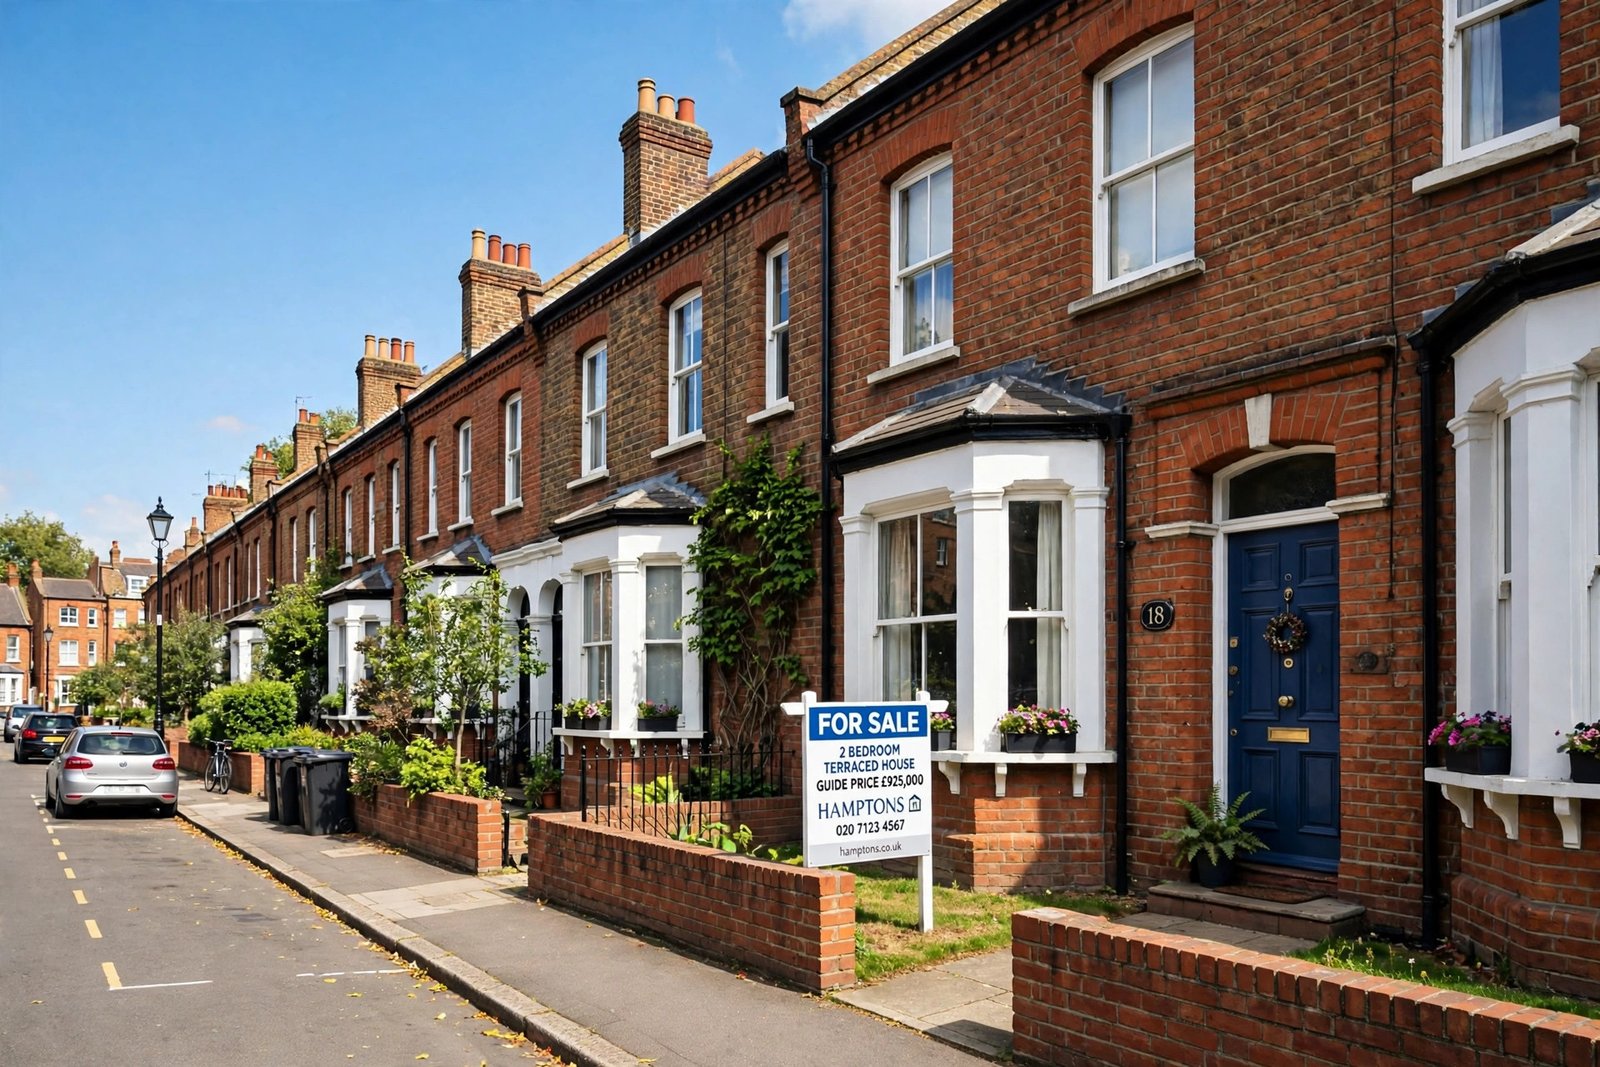
Yes, a foreigner can buy property in the United Kingdom. There is no visa requirement and no nationality condition for owning a home in the UK. You can live abroad, hold a passport from any country, and still buy a flat in London, a house in Manchester, or a buy-to-let property in the North East. Ownership and immigration are completely separate — buying a home does not give you a visa, and you do not need a visa to buy a home.
That open door is one reason the UK stays popular with overseas buyers. But the UK has its own taxes and legal process, and rules that treat non-resident buyers differently from local buyers. The biggest cost after the price is stamp duty, and for a foreign buyer that bill is higher. This guide walks through the whole process in plain language: who can buy, the steps in order, exactly what stamp duty you will pay, the taxes that follow, and the mistakes that catch overseas buyers out. All tax figures are for England and Northern Ireland unless a section says otherwise, because Scotland and Wales run their own systems.
Who Can Buy Property in the UK?
Almost anyone. UK law places no restriction on property ownership by nationality or residence. You do not need to live in the UK, hold a UK visa, or have a UK bank account to buy a home, although a UK bank account makes paying for it much easier. Companies can also buy UK property, although companies face extra taxes that this guide covers later.
Before you start looking, get three things ready. First, proof of identity — usually a valid passport. Your solicitor must legally check who you are and where your money comes from; these anti-money-laundering checks apply to every buyer. Second, proof of funds — bank statements showing the money is yours and how you earned or saved it. Large transfers from abroad will be questioned, so keep the paper trail clean. Third, a solicitor or licensed conveyancer. In England and Wales, choose one who has worked with overseas buyers before: they handle the contract, the searches, the tax return and the registration of your ownership.
Think early about how you will pay. Many overseas buyers pay cash, which is faster and simpler. If you need a mortgage, expect a larger deposit than a local buyer — often 25% or more — plus proof of income from your home country, usually translated into English. A broker who works with overseas clients can save you wasted applications. For a fuller step-by-step guide, see this guide to buying property in the UK.
The Buying Steps, in Order
Buying a home in England and Wales follows a fixed sequence. Knowing the order helps you plan your time and your money.
- Set your budget and your goal. Decide how much you can spend in total, including the price, stamp duty, solicitor’s fees, survey and moving costs. Decide too whether the home is for you to live in, a rental investment, or a long-term hold — that choice changes which cities and property types make sense.
- Get your money and documents ready. Have your passport and proof of funds in hand. If you are borrowing, get a mortgage agreement in principle before you offer — it shows the seller you are serious and confirms what you can borrow.
- Find a property and make an offer. Offers are made through the estate agent. Until contracts are exchanged, either side can still walk away, so do not spend large sums on surveys or legal work before your offer is accepted.
- Instruct your solicitor and order a survey. Your solicitor checks the title, planning history, flood risk and local charges. A survey checks the physical condition — for an older property, a full building survey is worth the money, as it can uncover damp, roof problems or subsidence that photos never show.
- Exchange contracts. This is the point the purchase becomes legally binding. You pay the deposit, usually 10% of the price, and agree the completion date. If you pull out after exchange, you lose the deposit.
- Complete the purchase. On completion day your solicitor sends the balance to the seller’s solicitor, the keys are released to you, and your solicitor pays the stamp duty and files the tax return.
- Register your ownership. Your solicitor registers the transfer with HM Land Registry, which records you as the legal owner. Keep every document — the contract, the survey, the completion statement — for tax when you rent or sell later.
The process usually takes eight to twelve weeks from an accepted offer to completion, longer if a chain of buyers and sellers is involved. Buying a new-build home can be faster, but read the contract carefully — new-build contracts often have long completion dates and strict deposit terms.
Stamp Duty: What You Will Pay
Stamp Duty Land Tax, or SDLT, is the tax you pay when you buy property in England and Northern Ireland. It is charged in bands, so you pay the rate for each slice of the price, not a single rate on the whole price. These are the standard rates for a main home since 1 April 2025:
| Price band | Standard SDLT rate |
|---|---|
| Up to £125,000 | 0% |
| £125,001 to £250,000 | 2% |
| £250,001 to £925,000 | 5% |
| £925,001 to £1,500,000 | 10% |
| Above £1,500,000 | 12% |
So on a £400,000 home, you pay nothing on the first £125,000, 2% on the next £125,000 (£2,500), and 5% on the remaining £150,000 (£7,500) — a total of £10,000.
The Non-Resident Surcharge and the Extra-Home Surcharge
Two surcharges can apply on top of the standard rates, and both matter to overseas buyers.
The non-resident surcharge is +2% on every band, and has applied since 1 April 2021. You count as non-resident if you have not spent at least 183 days in the UK in the 12 months before the purchase. Most buyers living abroad will pay it. If you move to the UK after buying and spend 183 days there within a year, you can claim the surcharge back.
The additional-dwelling surcharge is +5% on every band, and has applied since 31 October 2024. It applies if the home you are buying will not be your only residential property worth £40,000 or more anywhere in the world. So if you already own a home in your own country, or another property anywhere, and you buy a second home in the UK, the 5% surcharge applies — even if the first home is not in the UK.
If both surcharges apply, they stack: a non-resident buying an additional home pays +7% above the standard rate on every band. That is the most expensive combination, and the one many overseas investors face, because they usually already own a home in their own country.
Worked Example: A £1,000,000 Home
Here is what stamp duty looks like on a £1,000,000 home in England, in the three situations an overseas buyer might be in:
| Buyer situation | SDLT rates applied | Total SDLT |
|---|---|---|
| UK resident, only home | Standard rates (0%, 2%, 5%, 10%) | £43,750 |
| Non-resident, only home | Standard rates + 2% on every band | £63,750 |
| Non-resident, additional home | Standard rates + 7% on every band | £113,750 |
The difference is £70,000 between the cheapest and the most expensive case, on the same home at the same price. That is why it pays to check your residence status and your other properties before you offer. Remember these figures are the tax only — add the solicitor’s fees, the survey, the mortgage fee if you borrow, and the cost of moving money into the UK. On a £1,000,000 purchase, the total buying costs for a non-resident investor can easily reach £120,000 or more.
First-Time Buyer Relief
If you have never owned a residential property anywhere in the world, first-time buyer relief can cut your stamp duty: 0% on the first £300,000 and 5% on the portion from £300,001 to £500,000. There is no relief on homes above £500,000 — above that price, you pay the standard rates on the whole price.
So a first-time buyer paying £450,000 owes nothing on the first £300,000 and 5% on the remaining £150,000, which is £7,500. Without the relief, the same home would cost £10,000 in stamp duty. The relief applies to the buyer, not the property, so if two people buy together and one of them has owned before, the relief is lost.
Scotland and Wales Are Different
The figures above apply to England and Northern Ireland. Scotland and Wales run their own property taxes.
Scotland uses Land and Buildings Transaction Tax (LBTT). There is no non-resident surcharge in Scotland, so a foreign buyer pays the same LBTT rates as a Scottish buyer. But Scotland charges an Additional Dwelling Supplement of 8% on additional homes since 5 December 2024 — higher than the 5% surcharge in England. If you are buying a second home in Edinburgh or Glasgow, budget for that 8%.
Wales uses Land Transaction Tax (LTT), with its own bands and additional-dwelling rates, unchanged for 2026–27. There is no non-resident surcharge in Wales either. If you are choosing between England, Scotland and Wales, compare the tax: on a second home, Scotland’s 8% supplement can make Wales or England cheaper, depending on the price.
After You Buy: Rent, Tax and Selling
Buying is only the first tax event. If you rent the property out, or sell it later, more rules apply.
Rental income and the Non-Resident Landlord Scheme. If you live abroad and rent out a UK property, your rent is handled under the Non-Resident Landlord Scheme. In practice, your letting agent or tenant deducts basic-rate tax from the rent before it reaches you, unless you register with HM Revenue and Customs to receive the rent without tax deducted. Either way, you must report the income. From 6 April 2027, property income is taxed at higher separate rates of 24%, 44% and 49% following Budget 2026, so run the numbers at the new rates before you buy for income. This guide to UK property tax for overseas investors explains the tax side in more detail.
Capital gains when you sell. If the property has gone up in value, you pay capital gains tax on the profit when you sell. Non-resident sellers must report the sale to HM Revenue and Customs and pay any tax due within 60 days of completion. That deadline is strict, and the tax is due even if you have already left the UK. Keep records of the purchase price, the buying costs, and any money spent improving the property — they all reduce the taxable gain.
Annual Tax on Enveloped Dwellings (ATED). If you buy through a company rather than in your own name, a separate annual tax called ATED applies to homes worth over £500,000. The 2026–27 charges are:
| Home value | ATED charge 2026–27 |
|---|---|
| Over £500,000 up to £1 million | £4,600 |
| Over £1 million up to £2 million | £9,450 |
| Over £2 million up to £5 million | £32,200 |
| Over £20 million | £303,450 |
ATED rises by 3.5% from 1 April 2027. There are reliefs — for example, if the company lets the property commercially to unconnected tenants — but claiming them needs paperwork every year. For most individual buyers, owning in your own name is simpler, and you avoid ATED entirely.
London: The Main Market for Overseas Buyers
London is where most overseas buyers start. It has the deepest market, the most international agents and solicitors, and the strongest resale demand. Prime central London — Chelsea, Kensington, Mayfair — attracts the biggest budgets, while outer London and commuter towns offer lower prices and better rental yields. This guide to buying property in London as an overseas buyer covers the areas and the process in detail. Browse live properties for sale and rent in London to see what your budget buys, and compare them with the best rental cities in the USA and UK if you are weighing the UK against the USA.
But London is not the only option. Manchester has become a favourite for overseas investors because prices are lower and rental demand from students and young professionals is strong — see properties for sale and rent in Manchester, UK. The North East offers some of the highest gross rental yields in the country, around 8%, though prices and rents are lower and resale can be slower. The right city depends on your goal: capital growth points to London and the South East, while rental income points north. Our guide to UK house prices in 2027 explains where prices are expected to fall and recover first.
Mistakes to Avoid
- Forgetting the surcharges. Many overseas buyers budget the standard stamp duty and then discover the 2% non-resident surcharge — or the 5% additional-home surcharge — at the last minute. Check both before you offer.
- Buying through a company without advice. A company can help with some taxes and hurt with others, especially ATED. Get specialist advice before you choose a company structure.
- Skipping the survey. A cheap survey can miss damp, roof damage and subsidence. On an older UK home, a full building survey is money well spent.
- Ignoring the 60-day capital gains deadline. Non-resident sellers must report and pay within 60 days of completion. Missing the deadline brings penalties.
- Assuming you can live in the home. Buying property gives you no visa and no right to live in the UK. Your stays are still governed by immigration rules.
- Sending money to someone you have not verified. Use a regulated solicitor and a licensed estate agent. Never wire a deposit to a private individual on the basis of an online listing.
Frequently Asked Questions
Can a foreigner buy property in the UK without a visa?
Yes. There is no visa or nationality requirement for owning UK property. You can buy from abroad, pay cash or use a UK mortgage, and own the home outright. Owning it does not give you a visa or the right to live in the UK.
How much stamp duty does a foreign buyer pay in the UK?
It depends on the price, your residence and whether you own other property. Standard rates run from 0% to 12% in bands. Non-residents pay an extra 2% on every band, and buyers of an additional home pay an extra 5%. A non-resident buying an additional home pays 7% above standard on every band — £113,750 on a £1,000,000 home.
What is the 183-day rule for the non-resident surcharge?
You count as non-resident for stamp duty if you have not spent at least 183 days in the UK in the 12 months before the purchase. If you move to the UK afterwards and spend 183 days there within a year of buying, you can claim the 2% surcharge back.
Do I need a UK bank account to buy property?
It is not legally required, but it makes the purchase far easier — paying the deposit, the stamp duty, and later the bills and rent all run through it. Many UK banks open accounts for non-residents with a passport and proof of address from your home country.
Is stamp duty different in Scotland and Wales?
Yes. Scotland uses Land and Buildings Transaction Tax with an 8% Additional Dwelling Supplement since 5 December 2024 and no non-resident surcharge. Wales uses Land Transaction Tax, unchanged for 2026–27, with no non-resident surcharge. England and Northern Ireland use Stamp Duty Land Tax with the 2% non-resident surcharge and the 5% additional-dwelling surcharge.
Can I rent out a UK property I buy as a foreigner?
Yes. Rental income is taxed in the UK and handled under the Non-Resident Landlord Scheme if you live abroad. From 6 April 2027 property income is taxed at 24%, 44% and 49%. You must also follow the tenancy rules where the property sits — England, Scotland and Wales each have their own rental laws.
Start Looking at Real Properties
The UK is open to foreign buyers, the steps are clear, and the taxes — while higher for non-residents — are predictable once you know which surcharges apply to you. The next step is seeing what your money buys. Browse properties for sale and rent in the UK, compare prices in London and Manchester, and check the rents before you commit. Search everything on the properties listings page or the property search page. For a fuller picture, read whether UK house prices will fall in 2027 and the guide to buying property in the USA as a foreigner if you are comparing the two markets.